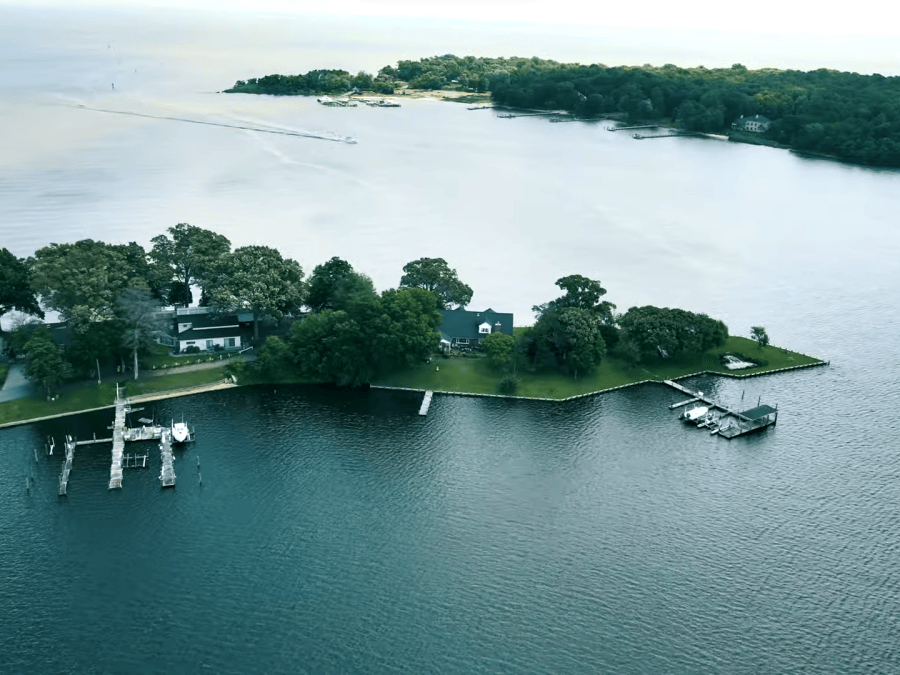Buying Your HomeThere's a Better Way to Buy
I had some fun with this one. Hit play, then we can talk about your search.
Online listings tell you the basics. Touring with a local agent helps you ask better questions about the property, location, and costs that come with owning it.
I’ll help you:
Buying from out of state? I can provide detailed live video tours and point out what catches my attention, including concerns that polished listing photos may not show. A virtual tour helps you evaluate a home, but does not replace an independent inspection.
Before We Tour: Understand Your Representation
It is a written agreement between you and the brokerage that describes the services provided, the scope and length of the relationship, compensation, and the responsibilities of each party. We’ll review it together before I begin working as your buyer’s agent, including before in-person or virtual home tours.
Yes. Services, duration, compensation, and other terms can be discussed before you sign. Compensation is not set by law. It must be clearly stated in the agreement, not left as an open-ended amount based on whatever a seller offers. Only sign when you understand the terms and they reflect what we agreed to.
That depends on the agreement and the transaction. A seller may offer compensation toward your buyer-broker fee, or you may ask for it as part of your offer. It is not guaranteed. You may be responsible for some or all of the fee under your agreement if another source does not cover it. Before touring, we’ll discuss the agreed fee, possible sources of payment, and your obligations. Before you make an offer, we’ll review the proposed arrangement for that property so you can plan for your potential out-of-pocket costs. Any credits or payments also need to work with your financing and applicable requirements.
Your agreement explains any exclusivity, which properties it covers, its end date, and how cancellation works. Read those terms before signing another agreement or asking another agent to arrange a showing. If you find a home yourself, send it to me so we can review it within the terms of our agreement.
The listing agent represents the seller unless a different lawful arrangement is disclosed and agreed to. Contacting an agent does not automatically give you your own representation. Ask whom the agent represents before sharing information about your budget or negotiating position.
I had some fun with this one. Hit play, then we can talk about your search.
A lender’s maximum approval and your comfortable monthly payment may be different numbers. Before we narrow the search, consider your savings, income, existing debt, and what you want left over each month.
A lender can review your credit, income, assets, and debts, explain financing options, and provide a preapproval based on your circumstances. Preapproval is not a final loan commitment. Keep your lender informed about changes to your finances during the purchase.
Buy with Real Creative Group and receive up to $1,200 in credits plus a $500 donation to a local scholarship fund in your name.
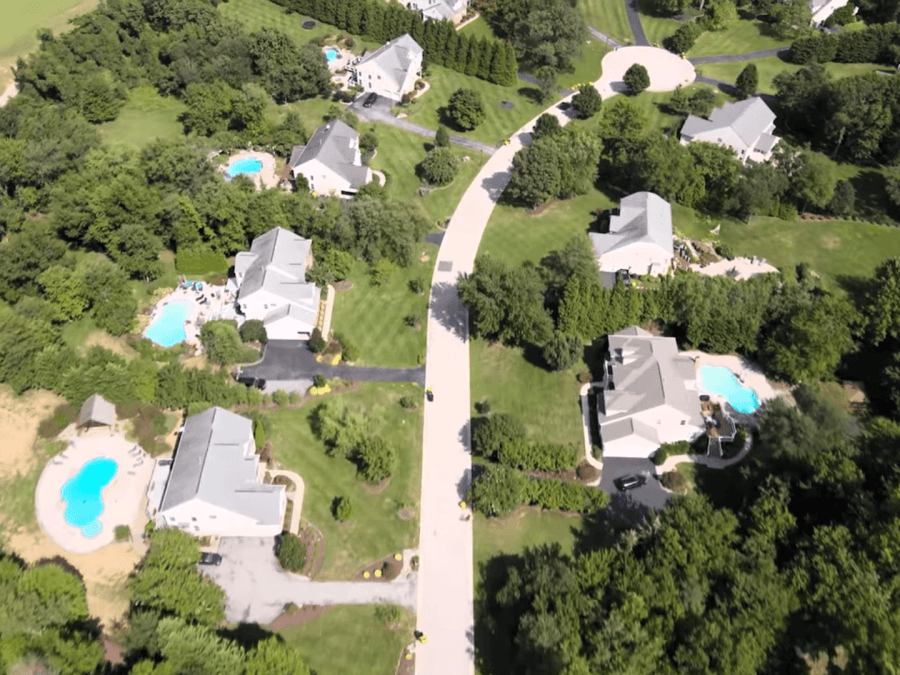
Start with my community tours to get a feel for Pasadena and nearby Anne Arundel County neighborhoods. Then we can compare homes around the things you care about, from your daily drive to the kind of outdoor space you want.
Want market context before touring? Explore Market Pulse for county-wide data. I’ll help you put those numbers in context for the homes you’re considering.

The right offer is not always the highest price or the fewest protections. We’ll compare relevant sales, assess the competition we can verify, and decide how to balance your budget, timing, and risk.
The right offer is not always the highest price or the fewest protections. We'll compare relevant sales, assess the competition we can verify, and decide how to balance your budget, timing, and risk.
Negotiations
We’ll review the asking price alongside comparable sales and your financing. A preapproval or proof of funds helps document your ability to purchase, but the full terms still matter.
Your deposit is a good-faith payment handled according to the contract and credited toward your purchase at settlement. The amount, delivery deadline, holder, and conditions for return are contract terms. Missing a deadline or defaulting can put the deposit at risk.
Inspection, financing, appraisal, and home-sale contingencies can provide protections when written into the contract. We’ll discuss what each does, the deadlines involved, and the risks before you consider limiting or waiving one.
Seller credits can help with permitted closing costs, subject to lender and loan-program limits. Requests for buyer-broker compensation also need clear terms. We’ll consider how the complete offer affects both your cash needs and the seller’s net proceeds.
The closing date needs to work for your lender and the parties involved. Possession is a separate issue. Any post-settlement occupancy needs a written agreement, appropriate protections, and lender approval where required.
An independent home inspector helps you evaluate the property’s condition. Depending on the home, additional specialists may be appropriate. Attend when possible, ask questions, and use the findings to understand immediate concerns and future maintenance. We’ll review any inspection rights and deadlines in your contract before deciding whether to request repairs, seek a credit, proceed, or consider a permitted termination. The seller does not automatically have to agree to your requests.
An appraisal is an opinion of value used by the lender. It is not a home inspection or a guarantee of a home’s condition or resale value. If the appraisal is below the purchase price, possible paths may include renegotiating, bringing additional funds if feasible, or exercising a contractual right to terminate. Your options and deposit protection depend on your agreement, financing, and deadlines. A higher appraisal does not guarantee a future profit.
Keep responding to your lender’s requests, avoid financial changes without consulting the lender, and stay aware of contingency dates. I’ll help coordinate the transaction, but you should never assume a deadline has been extended without the required agreement.
The closing date needs to work for your lender and the parties involved. Possession is a separate issue. Any post-settlement occupancy needs a written agreement, appropriate protections, and lender approval where required.
An independent home inspector helps you evaluate the property’s condition. Depending on the home, additional specialists may be appropriate. Attend when possible, ask questions, and use the findings to understand immediate concerns and future maintenance.
We’ll review any inspection rights and deadlines in your contract before deciding whether to request repairs, seek a credit, proceed, or consider a permitted termination. The seller does not automatically have to agree to your requests.
An appraisal is an opinion of value used by the lender. It is not a home inspection or a guarantee of a home’s condition or resale value.
If the appraisal is below the purchase price, possible paths may include renegotiating, bringing additional funds if feasible, or exercising a contractual right to terminate. Your options and deposit protection depend on your agreement, financing, and deadlines. A higher appraisal does not guarantee a future profit.
Keep responding to your lender’s requests, avoid financial changes without consulting the lender, and stay aware of contingency dates. I’ll help coordinate the transaction, but you should never assume a deadline has been extended without the required agreement.
Questions during the process? Call 410-971-8004.
Before settlement, we'll review the property's condition at the final walk-through and check agreed items under your contract. Review your Closing Disclosure and settlement figures with your lender and settlement provider, and ask questions about anything you do not understand.
Your settlement provider will explain what identification and funds you need. Independently verify wiring instructions using a trusted phone number before sending money. Do not rely on an unexpected email with changed instructions.
Signing is one part of closing. Your settlement provider will confirm completion and when keys and possession transfer under the contract.